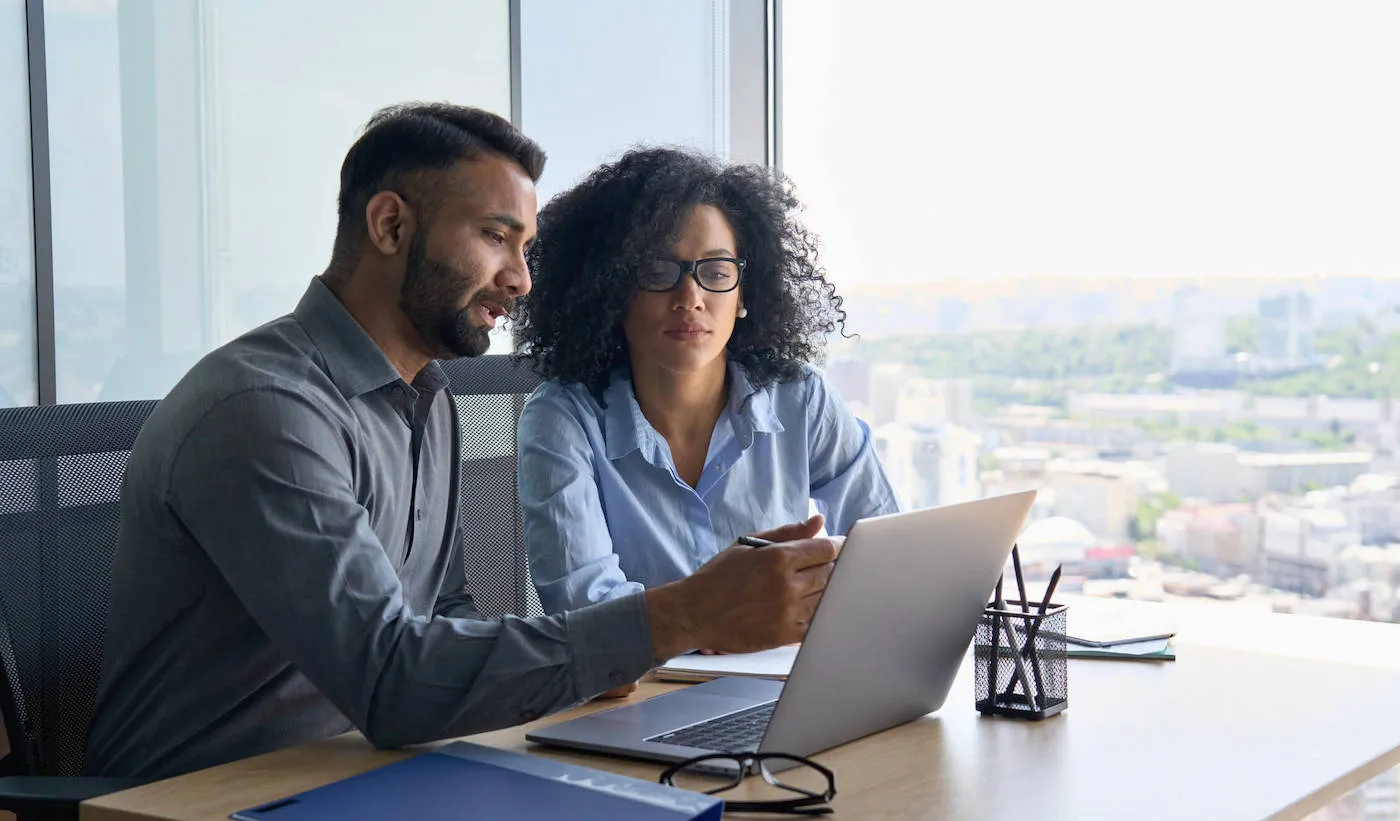
People who put money into an employer-sponsored retirement plan should be aware of an important word: “vested.” When you’re vested in a retirement plan, it means you own some or all of the money in your account. So, if you’re 100% vested, you own 100% of your retirement funds. But if you’re 20% vested, you’re entitled to all of the money you’ve contributed and just 20% of your employer’s matching contributions. Knowing what it means to be vested can make a difference in how much money you’ll have in your account for retirement or when you leave the company. Follow along to find out more about vesting………Continue reading..
Source: Experian
.
Critics:
Pensions should not be confused with severance pay; the former is usually paid in regular amounts for life after retirement, while the latter is typically paid as a fixed amount after involuntary termination of employment before retirement. The terms “retirement plan” and “superannuation” tend to refer to a pension granted upon retirement of the individual; the terminology varies between countries.
Retirement plans may be set up by employers, insurance companies, the government, or other institutions such as employer associations or trade unions. Called retirement plans in the United States, they are commonly known as pension schemes in the United Kingdom and Ireland and superannuation plans (or super) in Australia and New Zealand. Retirement pensions are typically in the form of a guaranteed life annuity, thus insuring against the risk of longevity.
The common use of the term pension is to describe the payments a person receives upon retirement, usually under predetermined legal or contractual terms. A recipient of a retirement pension is known as a pensioner or retiree. A retirement plan is an arrangement to provide people with an income during retirement when they are no longer earning a steady income from employment.
Often retirement plans require both the employer and employee to contribute money to a fund during their employment in order to receive defined benefits upon retirement. It is a tax deferred savings vehicle that allows for the tax-free accumulation of a fund for later use as retirement income. Funding can be provided in other ways, such as from labor unions, government agencies, or self-funded schemes. Pension plans are therefore a form of “deferred compensation”.
A SSAS is a type of employment-based Pension in the UK. The 401(k) is the iconic self-funded retirement plan that many Americans rely on for much of their retirement income; these sometimes include money from an employer, but are usually mostly or entirely funded by the individual using an elaborate scheme where money from the employee’s paycheck is withheld, at their direction, to be contributed by their employer to the employee’s plan. This money can be tax-deferred or not, depending on the exact nature of the plan.
Some countries also grant pensions to military veterans. Military pensions are overseen by the government; an example of a standing agency is the United States Department of Veterans Affairs. Ad hoc committees may also be formed to investigate specific tasks, such as the U.S. Commission on Veterans’ Pensions (commonly known as the “Bradley Commission”) in 1955–56. Pensions may extend past the death of the veteran himself, continuing to be paid to the widow.
Many countries have created funds for their citizens and residents to provide income when they retire (or in some cases become disabled). Typically this requires payments throughout the citizen’s working life in order to qualify for benefits later on. A basic state pension is a “contribution based” benefit, and depends on an individual’s contribution history. For examples, see National Insurance in the UK, or Social Security in the United States of America.
Many countries have also put in place a “social pension”. These are regular, tax-funded non-contributory cash transfers paid to older people. Over 80 countries have social pensions. Some are universal benefits, given to all older people regardless of income, assets or employment record. Examples of universal pensions include New Zealand Superannuation and the Basic Retirement Pension of Mauritius. Most social pensions, though, are means-tested, such as Supplemental Security Income in the United States of America or the “older person’s grant” in South Africa.
Some pension plans will provide for members in the event they suffer a disability. This may take the form of early entry into a retirement plan for a disabled member below the normal retirement age. The benefits of defined benefit and defined contribution plans differ based on the degree of financial security provided to the retiree. With defined benefit plans, retirees receive a guaranteed payout at retirement, determined by a fixed formula based on factors such as salary and years of service.
The risk and responsibility of ensuring sufficient funding through retirement is borne by the employer or plan managers. This type of plan provides a level of financial security for retirees, ensuring they will receive a specific amount of income throughout their retirement years. However this income is not usually guaranteed to keep up with inflation, so its purchasing power may decline over the years.
On the other hand, defined contribution plans are dependent upon the amount of money contributed and the performance of the investment vehicles used. Employees are responsible for ensuring that their contributions are sufficient to provide for their retirement needs, and they face the risk of market fluctuations that could reduce their retirement savings. However, defined contribution plans provide more flexibility for employees, who can choose how much to contribute and how to invest their funds.
Hybrid plans, such as cash balance and pension equity plans, combine features of both defined benefit and defined contribution plans. These plans have become increasingly popular in the U.S. since the 1990s. Cash balance plans, for example, provide a guaranteed benefit like a defined benefit plan, but the benefit is expressed as an account balance, like a defined contribution plan. Pension equity plans are a type of cash balance plan that credits employee accounts with a percentage of their pay each year, similar to a defined contribution plan.
A Defined Benefit (DB) pension plan is a plan in which workers accrue pension rights during their time at a firm and upon retirement the firm pays them a benefit that is a function of that worker’s tenure at the firm and of their earnings. In other words, a DB plan is a plan in which the benefit on retirement is determined by a set formula, rather than depending on investment returns. Government pensions such as Social Security in the United States are a type of defined benefit pension plan.
Traditionally, defined benefit plans for employers have been administered by institutions which exist specifically for that purpose, by large businesses, or, for government workers, by the government itself. A traditional form of defined benefit plan is the final salary plan, under which the pension paid is equal to the number of years worked, multiplied by the member’s salary at retirement, multiplied by a factor known as the accrual rate. The final accrued amount is available as a monthly pension or a lump sum, but usually monthly.
In the US, 26 U.S.C. § 414 specifies a defined benefit plan to be any pension plan that is not a defined contribution plan (see below) where a defined contribution plan is any plan with individual accounts. A traditional pension plan that defines a benefit for an employee upon that employee’s retirement is a defined benefit plan. In the U.S., corporate defined benefit plans, along with many other types of defined benefit plans, are governed by the Employee Retirement Income Security Act of 1974 (ERISA).
If the pension plan allows for early retirement, payments are often reduced to recognize that the retirees will receive the payouts for longer periods of time. In the United States, under the Employee Retirement Income Security Act of 1974, any reduction factor less than or equal to the actuarial early retirement reduction factor is acceptable.
Many DB plans include early retirement provisions to encourage employees to retire early, before the attainment of normal retirement age (usually age 65). Companies would rather hire younger employees at lower wages. Some of those provisions come in the form of additional temporary or supplemental benefits, which are payable to a certain age, usually before attaining normal retirement age. Due to changes in pensions over the years, many pension systems, including those in Alabama, California, Indiana, and New York, have shifted to a tiered system.
For a simplified example, suppose there are three employees that pay into a state pension system: Sam, Veronica, and Jessica. The state pension system has three tiers: Tier I, Tier II, and Tier III. These three tiers are based on the employee’s hire date (i.e. Tier I covers 1 January 1980 (and before) to 1 January 1995, Tier II 2 January 1995 to 1 January 2010, and Tier III 1 January 2010 to present) and have different benefit provisions (e.g. Tier I employees can retire at age 50 with 80% benefits or wait until 55 with full benefits, Tier II employees can retire at age 55 with 80% benefits or wait until 60 for full benefits, Tier III employees can retire at age 65 with full benefits).
Therefore, Sam, hired in June 1983, would be subject to the provisions of the Tier I scheme, whereas Veronica, hired in August 1995, would be permitted to retire at age 60 with full benefits and Jessica, hired in December 2014, would not be able to retire with full benefits until she became 65. In an unfunded defined benefit pension, no assets are set aside and the benefits are paid for by the employer or other pension sponsor as and when they are paid. Pension arrangements provided by the state in most countries in the world are unfunded, with benefits paid directly from current workers’ contributions and taxes.
This method of financing is known as pay-as-you-go, or PAYGO. The social security systems of many European countries are unfunded, having benefits paid directly out of current taxes and social security contributions, although several countries have hybrid systems which are partially funded. Spain set up the Social Security Reserve Fund and France set up the Pensions Reserve Fund; in Canada the wage-based retirement plan (CPP) is partially funded, with assets managed by the CPP Investment Board while the U.S. Social Security system is partially funded by investment in special U.S. Treasury Bonds.
In a funded plan, contributions from the employer, and sometimes also from plan members, are invested in a fund towards meeting the benefits. All plans must be funded in some way, even if they are pay-as-you-go, so this type of plan is more accurately known as pre-funded or fully-funded. The future returns on the investments, and the future benefits to be paid, are not known in advance, so there is no guarantee that a given level of contributions will be enough to meet the benefits.
Typically, the contributions to be paid are regularly reviewed in a valuation of the plan’s assets and liabilities, carried out by an actuary to ensure that the pension fund will meet future payment obligations. This means that in a defined benefit pension, investment risk and investment rewards are typically assumed by the sponsor/employer and not by the individual. If a plan is not well-funded, the plan sponsor may not have the financial resources to continue funding the plan.
CentraCare Workers Announce $800,000 Retirement Plan Settlement
.
RetirementPlan ,Investment ,FinancialFreedom ,WealthBuilding ,FuturePlanning ,RetirementSavings ,InvestSmart ,FinancialPlanning ,SecureYourFuture ,GrowYourWealth ,SmartInvesting ,RetirementGoals ,WealthManagement ,InvestmentStrategy ,LongTermInvesting ,FinancialLiteracy ,PassiveIncome ,RetirementWealth ,PlanForRetirement



Leave a Reply