Showing posts with label FinancialEducation. Show all posts

Monday, November 2, 2026

The One NeoCloud Stock To Buy Now

NeoCloud stocks have sold off as investors question whether specialized AI infrastructure providers can afford their ambitious expansion plans. A NeoCloud is a cloud provider focused on supplying the GPU-intensive computing capacity used to train and run AI models. Among the names I follow, Nebius Group N.V. (NBIS) is the one I favor buying amid the weakness. In my October 27 episode of Being Exponential, I explained why the recent pressure on AI infrastructure stocks doesn’t mean the AI computing boom is finished. It means investors need to get much more selective about which companies can fund the next phase of growth………Continue reading….

By Luke Lango and the InvestorPlace Research Staff

Source: InvestorPlace

.

Critics:

The stock market is one of the most important ways for companies to raise money, along with debt markets which are generally more imposing but do not trade publicly. This allows businesses to be publicly traded, and raise additional financial capital for expansion by selling shares of ownership of the company in a public market.

The liquidity that an exchange affords the investors enables their holders to quickly and easily sell securities. This is an attractive feature of investing in stocks, compared to other less liquid investments such as property and other immoveable assets. History has shown that the price of stocks and other assets is an important part of the dynamics of economic activity, and can influence or be an indicator of social mood.

Therefore, central banks tend to keep an eye on the control and behavior of the stock market and, in general, on the smooth operation of financial system functions. Financial stability is the raison d’ĂȘtre of central banks. Exchanges also act as the clearinghouse for each transaction, meaning that they collect and deliver the shares, and guarantee payment to the seller of a security.

This eliminates the risk to an individual buyer or seller that the counterparty could default on the transaction. The smooth functioning of all these activities facilitates economic growth in that lower costs and enterprise risks promote the production of goods and services as well as possibly employment. In this way the financial system is assumed to contribute to increased prosperity, although some controversy exists as to whether the optimal financial system is bank-based or market-based.

Recent events such as the Global Financial Crisis have prompted a heightened degree of scrutiny of the impact of the structure of stock markets (called market microstructure), in particular to the stability of the financial system and the transmission of systemic risk. A transformation is the move to electronic trading to replace human trading of listed securities.

Changes in stock prices are mostly caused by external factors such as socioeconomic conditions, inflation, exchange rates. Intellectual capital does not affect a company stock’s current earnings. Intellectual capital contributes to a stock’s return growth. The efficient-market hypothesis (EMH) is a hypothesis in financial economics that states that asset prices reflect all available information at the current time.

The ‘hard’ efficient-market hypothesis does not explain the cause of events such as the crash in 1987, when the Dow Jones Industrial Average plummeted 22.6 percent—the largest-ever one-day fall in the United States. This event demonstrated that share prices can fall dramatically even though no generally agreed upon definite cause has been found: a thorough search failed to detect any ‘reasonable’ development that might have accounted for the crash.

It seems also to be true more generally that many price movements (beyond those which are predicted to occur ‘randomly’) are not occasioned by new information; a study of the fifty largest one-day share price movements in the United States in the post-war period seems to confirm this. A ‘soft’ EMH has emerged which does not require that prices remain at or near equilibrium, but only that market participants cannot systematically profit from any momentary ‘market anomaly‘.

For instance, some research has shown that changes in estimated risk, and the use of certain strategies, such as stop-loss limits and value at risk limits, theoretically could cause financial markets to overreact. But the best explanation seems to be that the distribution of stock market prices is non-Gaussian (in which case EMH, in any of its current forms, would not be strictly applicable). Other research has shown that psychological factors may result in exaggerated (statistically anomalous) stock price movements (contrary to EMH which assumes such behaviors ‘cancel out’).

Psychological research has demonstrated that people are predisposed to ‘seeing’ patterns, and often will perceive a pattern in what is, in fact, just noise, e.g. seeing familiar shapes in clouds or ink blots. In the present context, this means that a succession of good news items about a company may lead investors to overreact positively, driving the price up. A period of good returns also boosts the investors’ self-confidence, reducing their (psychological) risk threshold.

Another phenomenon—also from psychology—that works against an objective assessment is group thinking. As social animals, it is not easy to stick to an opinion that differs markedly from that of a majority of the group. An example with which one may be familiar is the reluctance to enter a restaurant that is empty; people generally prefer to have their opinion validated by those of others in the group.

In one paper the authors draw an analogy with gambling. In normal times the market behaves like a game of roulette; the probabilities are known and largely independent of the investment decisions of the different players. In times of market stress, however, the game becomes more like poker (herding behavior takes over). The players now must give heavy weight to the psychology of other investors and how they are likely to react psychologically.

Stock markets play an essential role in growing industries that ultimately affect the economy through transferring available funds from units that have excess funds (savings) to those who are suffering from funds deficit (borrowings) (Padhi and Naik, 2012). In other words, capital markets facilitate funds movement between the above-mentioned units. This process leads to the enhancement of available financial resources which in turn affects the economic growth positively.

Economic and financial theories argue that stock prices are affected by macroeconomic trends. Macroeconomic trends include such as changes in GDP, unemployment rates, national income, price indices, output, consumption, unemployment, inflation, saving, investment, energy, international trade, immigration, productivity, aging populations, innovations, international finance.

Increasing corporate profit, increasing profit margins, higher concentration of business, lower company income, less vigorous activity, less progress, lower investment rates, lower productivity growth, less employee share of corporate revenues, decreasing Worker to Beneficiary ratio (year 1960 5:1, year 2009 3:1, year 2030 2.2:1), increasing female to male ratio college graduates.

Therefore, the stock market may be swayed in either direction by press releases, rumors, euphoria and mass panic. Over the short-term, stocks and other securities can be battered or bought by any number of fast market-changing events, making the stock market behavior difficult to predict. Emotions can drive prices up and down, people are generally not as rational as they think, and the reasons for buying and selling are generally accepted.

Behaviorists argue that investors often behave irrationally when making investment decisions thereby incorrectly pricing securities, which causes market inefficiencies, which, in turn, are opportunities to make money.However, the whole notion of EMH is that these non-rational reactions to information cancel out, leaving the prices of stocks rationally determined.
London close: Stocks mixed after ECB rate cut ShareCast 21:41 

.

NeoCloudstock, StockMarketOutlook ,InvestSmart ,MarketTrends ,EconomicAnalysis ,InvestingTips ,FinancialEducation ,MarketInsight ,StockAnalysis ,InvestmentStrategy ,TradeSmart ,BullMarket ,BearMarket ,WealthBuilding ,StockMarketNews ,FinanceGoals ,LongTermInvesting ,WealthManagement ,MarketWatch,InvestmentOpportunities ,FutureInvestments

Sunday, October 25, 2026

How Cognitive Biases Can Negatively Affect Your Investment Decisions

The most significant foundational theories of modern finance, Modern Portfolio Theory and the Efficient Market Hypothesis, have an important assumption in common. In fact, academic research in finance and economics, as well as in many other social sciences, is based on the rational actor theory, which posits that people evaluate all information and options available to choose the one that maximizes benefits and minimizes costs. It wouldn’t make sense to do otherwise, would it? But real life rarely mirrors theory, and in real life investors aren’t rational……..…Continue reading….

By: Motley Fool Asset Management

Source: Motley Fool

.

Critics: 

Many social institutions rely on individuals to make rational judgments. Across management, finance, medicine, and law, the most recurrent bias is overconfidence, though anchoring and framing also play substantial roles. While research in finance often uses large-scale data, studies in medicine and law frequently rely on vignette-based designs. Berthet highlights the lack of ecological validity in many studies and the need for deeper exploration of individual differences in susceptibility to bias.

The securities regulation regime largely assumes that all investors act as perfectly rational persons. In truth, actual investors face cognitive limitations from biases, heuristics, and framing effects. In some academic disciplines, the study of bias is very popular. For instance, bias is a wide spread and well studied phenomenon because most decisions that concern the minds and hearts of entrepreneurs are computationally intractable.

In law enforcement and legal decision-making, confirmation bias and related errors frequently influence investigative decisions and evidence evaluation. Structured intervention strategies, such as accountability measures and checklists, show some promise in reducing bias during case evaluations. A fair jury trial, for example, requires that the jury ignore irrelevant features of the case, weigh the relevant features appropriately, consider different possibilities open-mindedly and resist fallacies such as appeal to emotion.

The various biases demonstrated in these psychological experiments suggest that people will frequently fail to do all these things. However, they fail to do so in systematic, directional ways that are predictable. Cognitive biases can create other issues that arise in everyday life. Study participants who ate more unhealthy snack food tended to have less inhibitory control and more reliance on approach bias.

Cognitive biases could be linked to various eating disorders and how people view their bodies and their body image. Cognitive biases can be used in destructive ways. Some believe that there are people in authority who use cognitive biases and heuristics in order to manipulate others so that they can reach their end goals. Some medications and other health care treatments rely on cognitive biases in order to persuade others who are susceptible to cognitive biases to use their products.

Many see this as taking advantage of one’s natural struggle of judgement and decision-making. They also believe that it is the government’s responsibility to regulate these misleading ads. Cognitive biases also seem to play a role in property sale price and value. Participants in the experiment were shown a residential property. Afterwards, they were shown another property that was completely unrelated to the first property. They were asked to say what they believed the value and the sale price of the second property would be.

They found that showing the participants an unrelated property did have an effect on how they valued the second property. Cognitive biases can be used in non-destructive ways. In team science and collective problem-solving, the superiority bias can be beneficial. It leads to a diversity of solutions within a group, especially in complex problems, by preventing premature consensus on suboptimal solutions.

This example demonstrates how a cognitive bias, typically seen as a hindrance, can enhance collective decision-making by encouraging a wider exploration of possibilities. Cognitive biases are interlinked with collective illusions, a phenomenon where a group of people mistakenly believe that their views and preferences are shared by the majority, when in reality, they are not. These illusions often arise from various cognitive biases that misrepresent our perception of social norms and influence how we assess the beliefs of others.

Cognitive biases also influence the spread of misinformation, particularly in digital environments. Lazer, Baum, and Grinberg (2018) analyzed over 16,000 false news stories shared by millions of Twitter users during the 2016 U.S. election and found that false information spread significantly faster than accurate news. This occurs partly because misinformation aligns with existing beliefs and triggers emotional reactions, both of which are linked to confirmation and availability biases.

These findings illustrate how cognitive biases can distort public understanding and contribute to the rapid dissemination of false narratives. The content and direction of cognitive biases are not “arbitrary”. Debiasing is the reduction of biases in judgment and decision-making through incentives, nudges, and training. Cognitive bias mitigation and cognitive bias modification are forms of debiasing specifically applicable to cognitive biases and their effects.

One debiasing technique aims to decrease biases by encouraging individuals to use controlled processing compared to automatic processing. Because they cause systematic errors, cognitive biases cannot be compensated for using a wisdom of the crowd technique of averaging answers from several people. Reference class forecasting is a method for systematically debiasing estimates and decisions, based on what Daniel Kahneman has dubbed the outside view.

Cognitive bias modification (CBM) refers to the process of modifying cognitive biases in healthy people and also refers to a growing area of psychological (non-pharmaceutical) therapies for anxiety, depression and addiction called cognitive bias modification therapy (CBMT). CBMT is sub-group of therapies within a growing area of psychological therapies based on modifying cognitive processes with or without accompanying medication and talk therapy, sometimes referred to as applied cognitive processing therapies (ACPT).

Although cognitive bias modification can refer to modifying cognitive processes in healthy individuals, CBMT is a growing area of evidence-based psychological therapy, in which cognitive processes are modified to relieve suffering from serious depression, anxiety, and addiction. CBMT techniques are technology-assisted therapies that are delivered via a computer with or without clinician support.

CBM combines evidence and theory from the cognitive model of anxiety, cognitive neuroscience, and attentional models. Even one-shot training interventions, such as educational videos and debiasing games that taught mitigating strategies, significantly reduced the commission of several cognitive biases. Cognitive bias modification has also been used to help those with obsessive-compulsive beliefs and obsessive-compulsive disorder. This therapy has shown that it decreases the obsessive-compulsive beliefs and behaviors.

In relation to reducing the fundamental attribution error, monetary incentives and informing participants they will be held accountable for their attributions have been linked to the increase of accurate attributions. Individual differences in cognitive bias have also been linked to varying levels of cognitive abilities and functions. The Cognitive Reflection Test (CRT) has been used to help understand the connection between cognitive biases and cognitive ability.

There have been inconclusive results when using the Cognitive Reflection Test to understand ability. However, there does seem to be a correlation; those who gain a higher score on the Cognitive Reflection Test, have higher cognitive ability and rational-thinking skills. This in turn helps predict the performance on cognitive bias and heuristic tests. Those with higher CRT scores tend to be able to answer more correctly on different heuristic and cognitive bias tests and tasks.

Age is another individual difference that has an effect on one’s ability to be susceptible to cognitive bias. Older individuals tend to be more susceptible to cognitive biases and have less cognitive flexibility. However, older individuals were able to decrease their susceptibility to cognitive biases throughout ongoing trials. These experiments had both young and older adults complete a framing task. Younger adults had more cognitive flexibility than older adults. Cognitive flexibility is linked to helping overcome pre-existing biases.

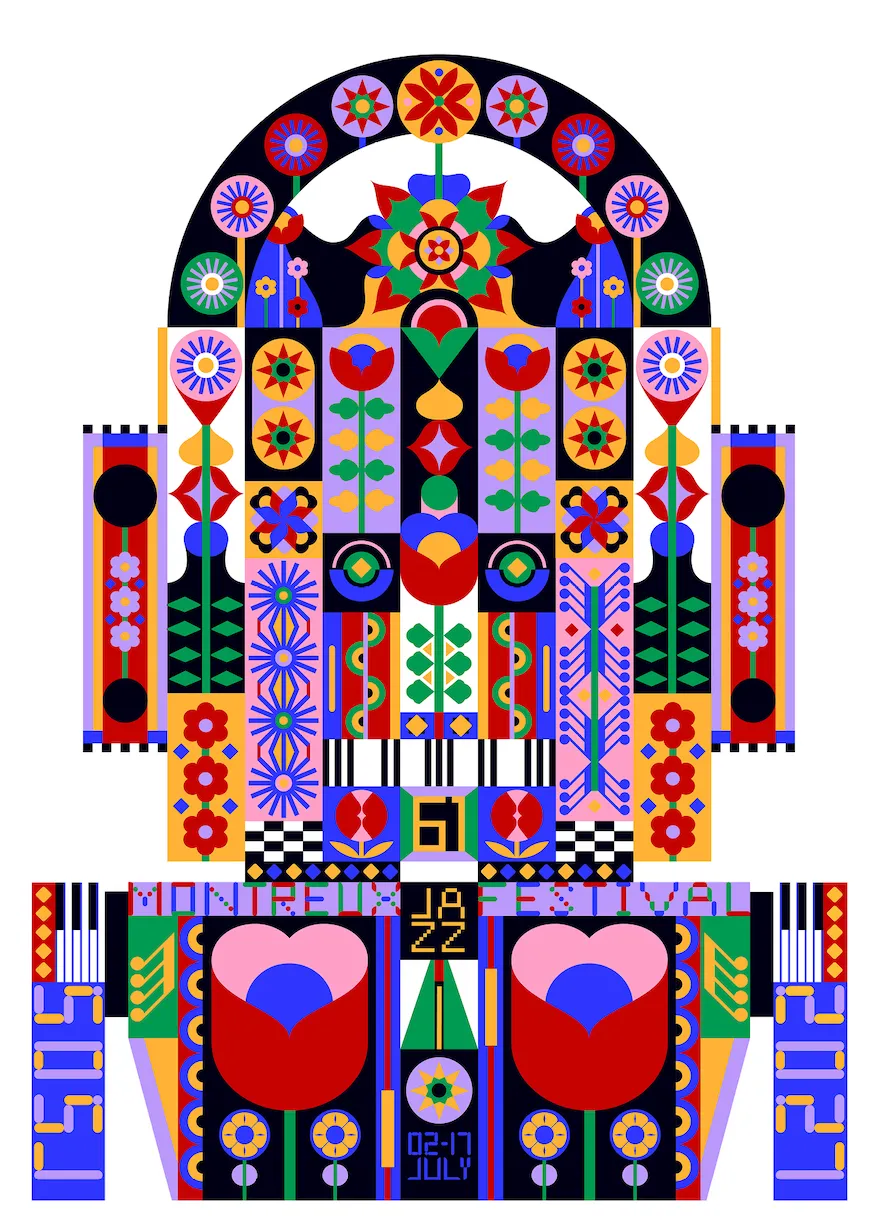
New 40 Years After Andy Warhol and Keith Haring, Montreux Jazz Festival’s Poster Is a Dream Creative Double Act

Image Credit: Montreux Jazz Festival Montreux has a long history of artist-designed posters. Other previous contributors have included David...