Showing posts with label RetirementGoals. Show all posts

Monday, October 12, 2026

Retiring At 36 Didn’t Make Me Happy. Heres what I did

Credit: Westend61, Getty Images

An eight-figure exit gave me endless free time and an identity crisis. Here is how to schedule joy, buy back your hours and choose where they go. At 36, I sold the fintech company I had spent years building and walked away with an eight-figure exit. No client needed an answer. No product roadmap demanded a decision. No inbox confirmed that I was useful. I thought it would feel like freedom. It felt like an identity crisis. As CEO, I had been time-starved but important. My calendar told me where to go, and my business card told me who I was………Continue reading..

.

Critics:

Many factors affect people’s retirement decisions. Retirement funding education is a big factor that affects the success of an individual’s retirement experience. Social Security plays an important role because most individuals solely rely on Social Security as their only retirement option, when Social Security’s trust funds are expected to be depleted by 2034.

Knowledge affects an individual’s retirement decisions by simply finding more reliable retirement options such as Individual Retirement Accounts or Employer-Sponsored Plans. In countries around the world, people are much more likely to retire at the early and normal retirement ages of the public pension system (e.g., ages 62 and 65 in the U.S.).
This pattern cannot be explained by different financial incentives to retire at these ages since typically retirement benefits at these ages are approximately actuarially fair; that is, the present value of lifetime pension benefits (pension wealth) conditional on retiring at age a is approximately the same as pension wealth conditional on retiring one year later at age a+1.

Nevertheless, a large literature has found that individuals respond significantly to financial incentives relating to retirement (e.g., to discontinuities stemming from the Social Security earnings test or the tax system). Greater wealth tends to lead to earlier retirement since wealthier individuals can essentially “purchase” additional leisure.

Generally, the effect of wealth on retirement is difficult to estimate empirically since observing greater wealth at older ages may be the result of increased saving over the working life in anticipation of earlier retirement. However, many economists have found creative ways to estimate wealth effects on retirement and typically find that they are small.

For example, one paper exploits the receipt of an inheritance to measure the effect of wealth shocks on retirement using data from the HRS. The authors find that receiving an inheritance increases the probability of retiring earlier than expected by 4.4 percentage points, or 12 percent relative to the baseline retirement rate, over an eight-year period.

A great deal of attention has surrounded how the Financial crisis of 2007–2008 and subsequent Great Recession are affecting retirement decisions, with the conventional wisdom saying that fewer people will retire since their savings have been depleted; however recent research suggests that the opposite may happen.

Using data from the HRS, researchers examined trends in defined benefit (DB) vs. defined contribution (DC) pension plans and found that those nearing retirement had only limited exposure to the recent stock market decline and thus are not likely to substantially delay their retirement.

At the same time, using data from the Current Population Survey (CPS), another study estimates that mass layoffs are likely to lead to an increase in retirement almost 50% larger than the decrease brought about by the stock market crash, so that on net retirements are likely to increase in response to the crisis.

More information tells of how many who retire will continue to work, but not in the career they have had for the majority of their life. Job openings will increase in the next 5 years due to retirements of the baby boomer generation. The Over 50 population is actually the fastest growing labor groups in the US.

A great deal of research has examined the effects of health status and health shocks on retirement. It is widely found that individuals in poor health generally retire earlier than those in better health. This does not necessarily imply that poor health status leads people to retire earlier, since in surveys retirees may be more likely to exaggerate their poor health status to justify their earlier decision to retire.

This justification bias, however, is likely to be small. In general, declining health over time, as well as the onset of new health conditions, have been found to be positively related to earlier retirement.Health conditions that can cause someone to retire include hypertension, diabetes mellitus, sleep apnea, joint diseases, and hyperlipidemia.

Most people are married when they reach retirement age; thus, spouse’s employment status may affect one’s decision to retire. On average, husbands are three years older than their wives in the U.S., and spouses often coordinate their retirement decisions. Thus, men are more likely to retire if their wives are also retired than if they are still in the labor force, and vice versa.
.

RetirementPlanning ,FinancialFreedom ,FuturePlanning ,WealthManagement ,RetirementGoals ,SavingsStrategies ,FinancialLiteracy ,InvestSmart ,MoneyMatters ,RetireHappy ,RetirementSavings ,FinancialSecurity ,LongTermVision ,SmartInvesting ,SecureYourFuture ,WealthBuilding ,LifeAfterWork ,RetirementTips ,RetirementAdvice

Thursday, July 30, 2026

Best Retirement Plans Of 2026 

Photo: Getty

There is a wide range of tax-advantaged retirement accounts to help you save for the golden years, including employer-sponsored plans and accounts you can open independently. But which is right for you? Each type of account has different contribution limits and requirements. Below, we review features and rules for the best retirement plans. Traditional individual retirement accounts (IRAs) and Roth IRAs are the most common types of retirement plans for individuals…….Continue reading….

By:  Taylor Medine

Source: Forbes Advisor

.

Critics:

Portfolio managers make decisions about investment mix and policy, matching investments to objectives, asset allocation for individuals and institutions, and balancing risk against performance. Portfolio management is about strengths, weaknesses, opportunities, and threats in the choice of debt vs. equity, domestic vs. international, growth vs. safety, and other trade-offs encountered in the attempt to maximize return at a given appetite for risk.

Portfolio managers are presented with investment ideas by internal buy-side analysts and sell-side analysts from investment banks. It is their job to sift through the relevant information and use their judgment to buy and sell securities. Throughout the day they read reports, talk to company managers, and monitor industry and economic trends, looking for the right company and time to invest the portfolio’s capital.

A team of analysts and researchers are ultimately responsible for establishing an investment strategy, selecting appropriate investments, and allocating each investment properly for a fund or asset management vehicle. In the case of mutual and exchange-traded funds (ETFs), there are two forms of portfolio management: passive and active. Passive management simply tracks a market index, commonly referred to as indexing or index investing.

Active management involves a single manager, co-managers, or a team of managers who attempt to beat the market return by actively managing a fund’s portfolio through investment decisions based on research and decisions on individual holdings. Closed-end funds are generally actively managed.

Modern portfolio theory was introduced in a 1952 doctoral thesis by Harry Markowitz; see Markowitz model. It assumes that an investor wants to maximize a portfolio’s expected return contingent on any given amount of risk. For portfolios that meet this criterion, known as efficient portfolios, achieving a higher expected return requires taking on more risk, so investors are faced with a trade-off between risk and expected return.

This risk-expected return relationship of efficient portfolios is graphically represented by a curve known as the efficient frontier. All efficient portfolios, each represented by a point on the efficient frontier, are well-diversified. While ignoring higher moments can lead to significant over-investment in risky securities, especially when volatility is high,the optimization of portfolios when return distributions are non-Gaussian is mathematically challenging.

Portfolio optimization often takes place in two stages: optimizing weights of asset classes to hold, and optimizing weights of assets within the same asset class. An example of the former would be choosing the proportions placed in equities versus bonds, while an example of the latter would be choosing the proportions of the stock sub-portfolio placed in stocks X, Y, and Z. Equities and bonds have fundamentally different financial characteristics and have different systematic risk .

Hence can be viewed as separate asset classes; holding some of the portfolio in each class provides some diversification, and holding various specific assets within each class affords further diversification. By using such a two-step procedure one eliminates non-systematic risks both on the individual asset and the asset class level. For the specific formulas for efficient portfolios, see Portfolio separation in mean-variance analysis.

One approach to portfolio optimization is to specify a von Neumann–Morgenstern utility function defined over final portfolio wealth; the expected value of utility is to be maximized. To reflect a preference for higher rather than lower returns, this objective function is increasing in wealth, and to reflect risk aversion it is concave. For realistic utility functions in the presence of many assets that can be held, this approach, while theoretically the most defensible, can be computationally intensive.

Harry Markowitz developed the “critical line method”, a general procedure for quadratic programming that can handle additional linear constraints and upper and lower bounds on holdings. Moreover, in this context, the approach provides a method for determining the entire set of efficient portfolios. Its application here was later explicated by William Sharpe. Portfolio optimization is usually done subject to constraints, such as regulatory constraints, or illiquidity.

These constraints can lead to portfolio weights that focus on a small sub-sample of assets within the portfolio. When the portfolio optimization process is subject to other constraints such as taxes, transaction costs, and management fees, the optimization process may result in an under-diversified portfolio.

Investors may be forbidden by law to hold some assets. In some cases, unconstrained portfolio optimization would lead to short-selling of some assets. However short-selling can be forbidden. Sometimes it is impractical to hold an asset because the associated tax cost is too high. In such cases appropriate constraints must be imposed on the optimization process.

Transaction costs are the costs of trading in order to change the portfolio weights. Since the optimal portfolio changes with time, there is an incentive to re-optimize frequently. However, too frequent trading would incur too-frequent transactions costs; so the optimal strategy is to find the frequency of re-optimization and trading that appropriately trades off the avoidance of transaction costs with the avoidance of sticking with an out-of-date set of portfolio proportions.

This is related to the topic of tracking error, by which stock proportions deviate over time from some benchmark in the absence of re-balancing.Different approaches to portfolio optimization measure risk differently. In addition to the traditional measure, standard deviation, or its square (variance), which are not robust risk measures, other measures include the Sortino ratio, CVaR (Conditional Value at Risk), and statistical dispersion.

Investment is a forward-looking activity, and thus the covariances of returns must be forecast rather than observed. Portfolio optimization assumes the investor may have some risk aversion and the stock prices may exhibit significant differences between their historical or forecast values and what is experienced. In particular, financial crises are characterized by a significant increase in correlation of stock price movements which may seriously degrade the benefits of diversification.

In a mean-variance optimization framework, accurate estimation of the variance-covariance matrix is paramount. Quantitative techniques that use Monte-Carlo simulation with the Gaussian copula and well-specified marginal distributions are effective. Allowing the modeling process to allow for empirical characteristics in stock returns such as autoregression, asymmetric volatility, skewness, and kurtosis is important.

Not accounting for these attributes can lead to severe estimation error in the correlations, variances and covariances that have negative biases (as much as 70% of the true values). Other optimization strategies that focus on minimizing tail-risk (e.g., value at risk, conditional value at risk) in investment portfolios are popular amongst risk averse investors.

To minimize exposure to tail risk, forecasts of asset returns using Monte-Carlo simulation with vine copulas to allow for lower (left) tail dependence (e.g., Clayton, Rotated Gumbel) across large portfolios of assets are most suitable. (Tail) risk parity focuses on allocation of risk, rather than allocation of capital.

Leave a Reply

How To Handle Jealous Feelings

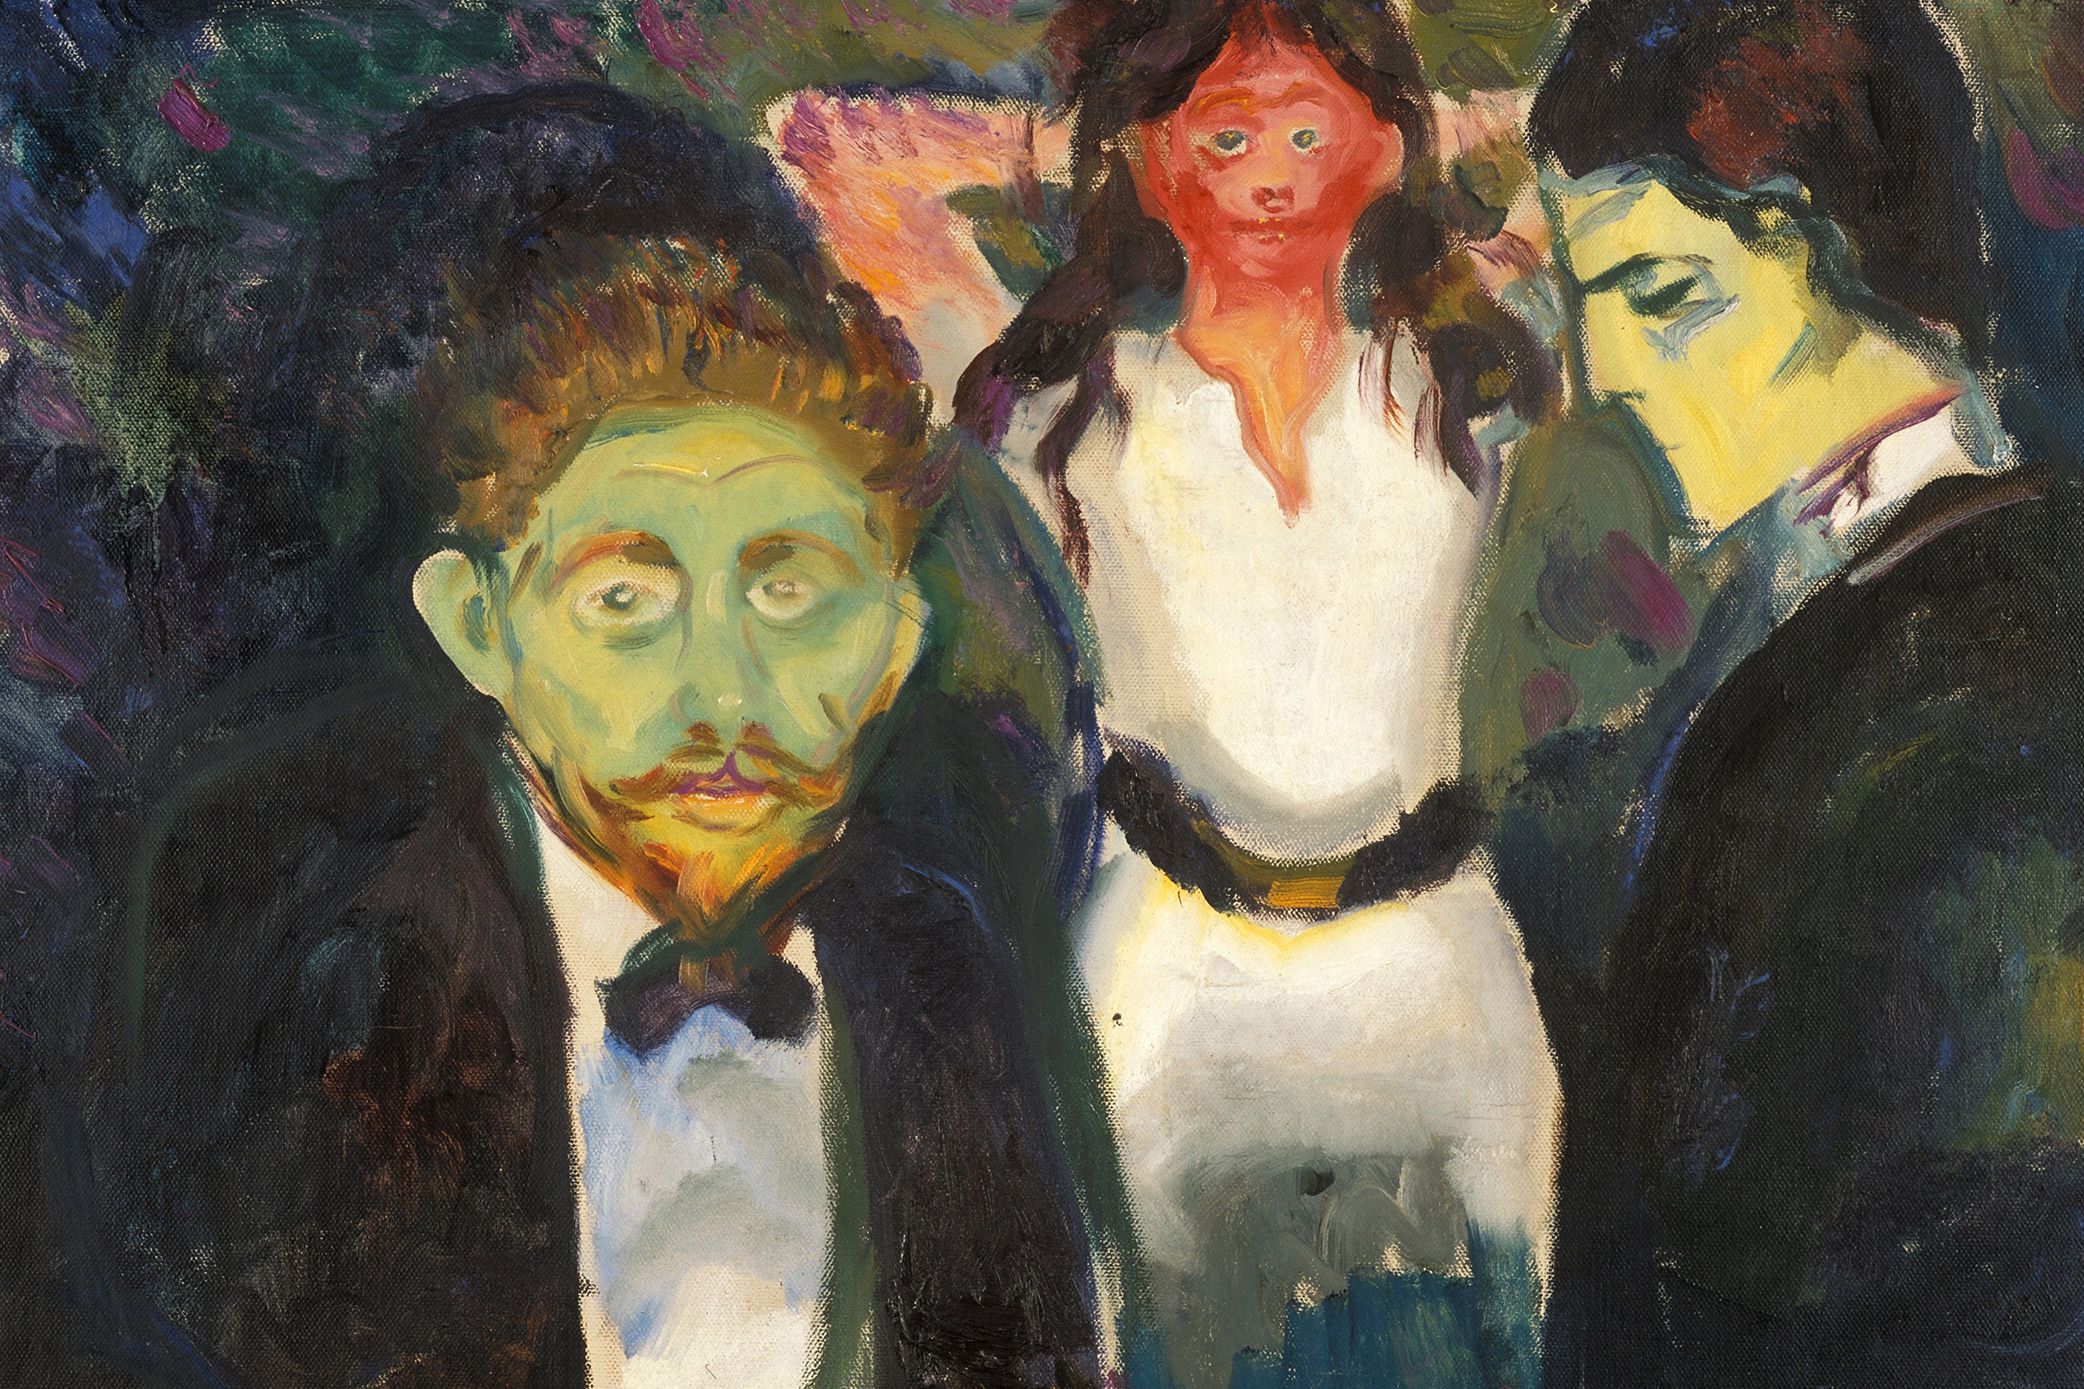
Jealousy (1907) by Edvard Munch. Courtesy the Munch Museum/Wikipedia Jealousy can rear its head in many ways. Have you ever felt displeased ...